Leverage is one of the most powerful tools in real estate investing. It allows investors to control valuable property with less of their own money by using borrowed capital. When a property performs well, leverage can improve returns on the investor’s original equity.
But leverage is not automatically an advantage.
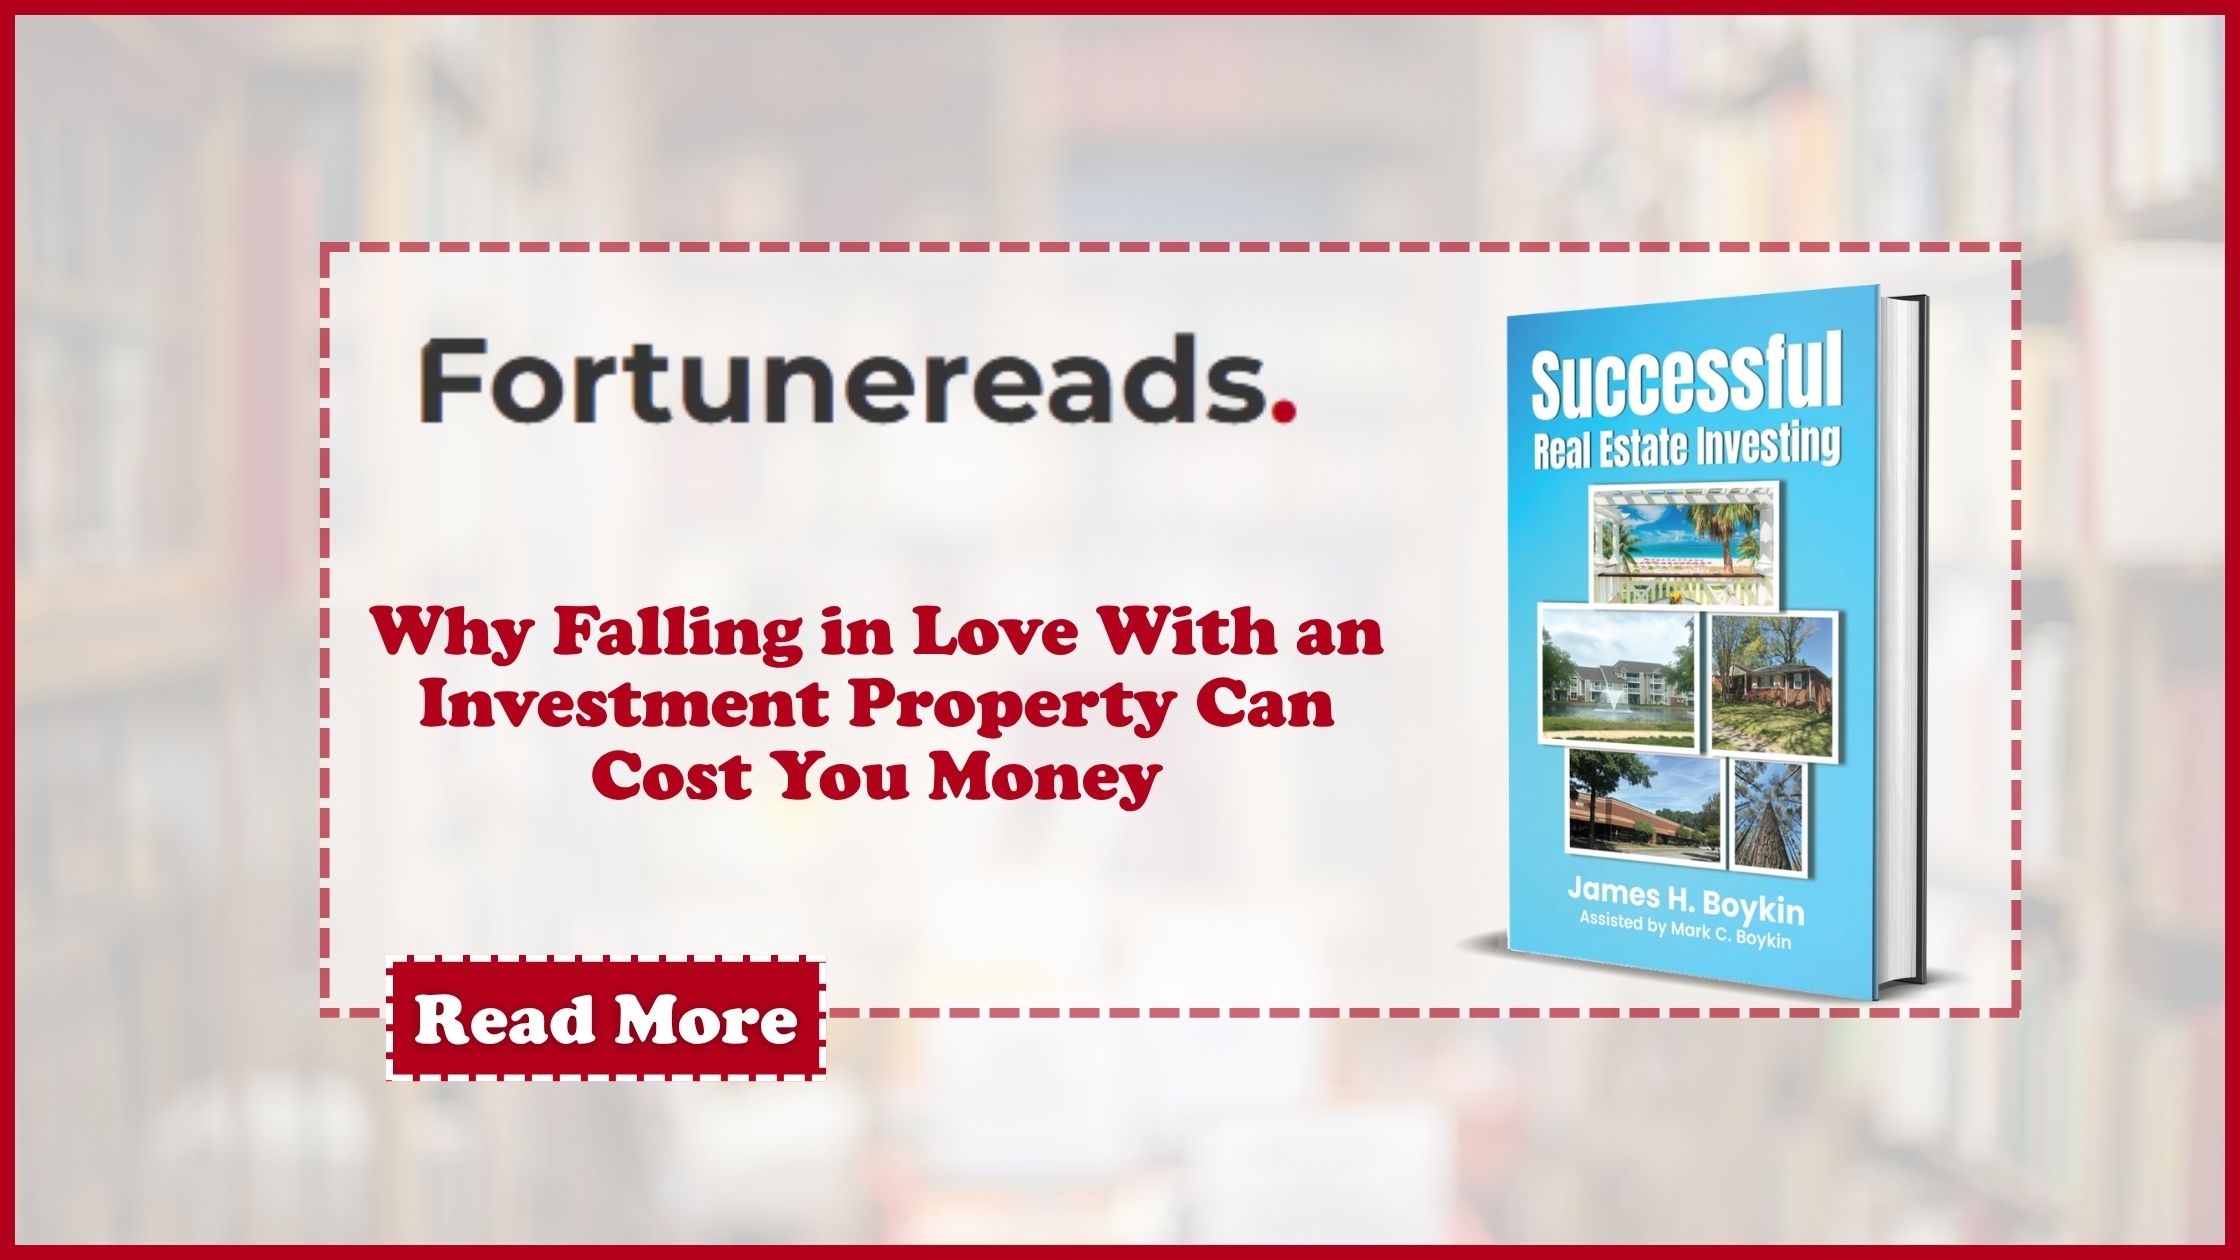
In Successful Real Estate Investing, James H. Boykin makes an important point: leverage magnifies financial results in both directions. It can increase returns when income and property performance are strong, but excessive debt can quickly become dangerous when vacancies rise, expenses increase or financing costs change.
Why Investors Are Attracted to Leverage
The appeal is easy to understand.
Instead of paying the full purchase price in cash, an investor can contribute a down payment and borrow the remainder. This allows the investor to preserve capital for other opportunities while benefiting from ownership of a larger asset.
Boykin illustrates how increasing loan-to-value ratios can produce higher returns on the investor’s initial equity when net operating income remains strong. In the book’s example, return on initial equity rises as leverage increases.
That can make leverage look extremely attractive.
However, those improved percentages do not tell the entire story.
Higher Debt Means Less Room for Error
More borrowing means higher debt service.
If rental income declines, tenants leave, repairs become more expensive or other operating costs rise, the property still has mortgage obligations. Higher leverage means a larger portion of the property’s income must go toward those payments.
Boykin captures the trade-off memorably: higher leverage may allow an investor to “eat better,” while lower leverage may allow the investor to “sleep better.”
The lesson is not that investors should avoid debt. Instead, they should understand how much risk comes with the debt they accept.
Interest Rates Can Change the Equation
Financing structure matters just as much as the amount borrowed.
Boykin warns about the danger of combining short-term loans, variable interest rates, optimistic underwriting and weakening occupancy. A property that appears profitable under one interest rate may experience reduced or even negative cash flow when borrowing costs increase.
In severe situations, the combination of rising rates and weak property performance can ultimately contribute to foreclosure.
That is why investors need to evaluate financing under less favorable scenarios, not merely under ideal conditions.
Cash Flow Deserves More Attention Than Excitement
A highly leveraged purchase can appear impressive on paper. Yet the real question is whether the property can reliably support its debt.
Investors need to examine net operating income, expected vacancies, operating expenses, reserves and debt coverage before deciding how aggressively to borrow. Boykin’s discussion of financial analysis emphasizes comparing a property’s financial ratios with regional benchmarks rather than relying only on seller projections.
That disciplined approach can expose risks before they become expensive problems.
Use Leverage as a Tool, Not a Shortcut
Successful Real Estate Investing by James H. Boykin presents real estate investing as a process of informed decision-making rather than easy wealth creation.
Leverage can help investors expand their purchasing power and increase returns. But when debt becomes excessive, the same force that magnifies gains can magnify losses.
The goal is not simply to borrow more.
It is to borrow intelligently.
Explore more practical guidance on financing, risk, property analysis and investment strategy in Successful Real Estate Investing by James H. Boykin.
Read the book on Amazon: https://a.co/d/0gjvN7zf